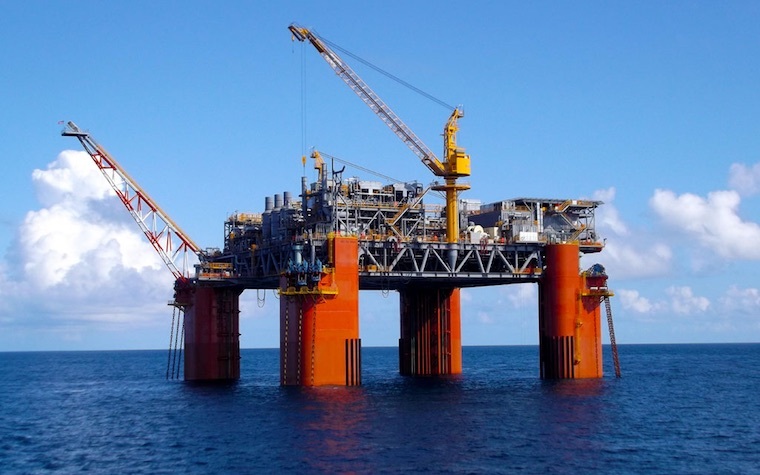
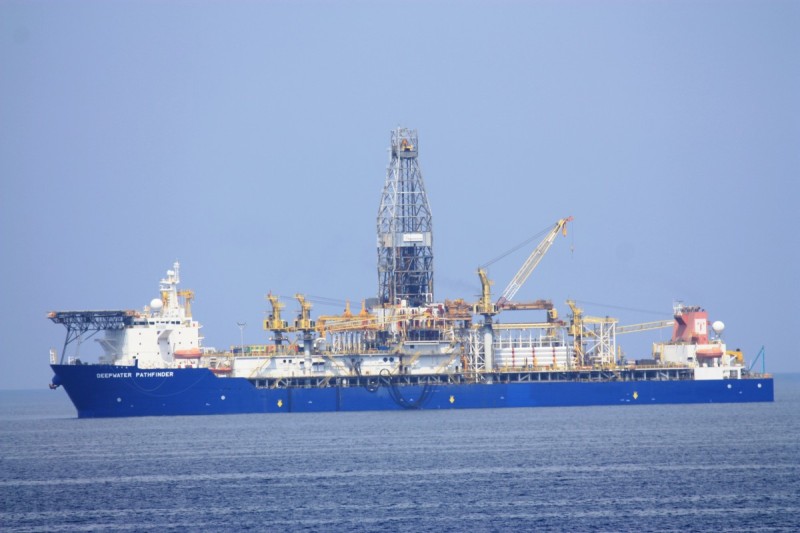
 A concise case study in when a jury may evaluate contractual intent appears in Apache Corp. v. W&T Offshore, No. 7-20599 (July 16, 2019), in which the parties disputed how their Joint Operating Agreement about an offshore drilling project dealt with a $40 million charge associated with using a particular drilling rig.
On the one hand, section 6.2 said that the operator “shall not make any single expenditure . . . costing $200,000 or more” unless an Authorization for Expenditure (“AFE”) is approved. A related provision, about accounting, says that an “acceptable reason[] for non-payment or short payment” includes the situation “when an AFE is not approved.” The defendant cited these provisions in declining to pay, arguing that it had not an AFE on the subject of the rig.
But the operator cited section 18.4, which addresses government-mandated plugging & abandonment operations, and said that the operator “[s]hall conduct” such activity as “required by a governmental authority,” with “the Costs, risks and net proceeds . . . shared by the Participating Parties in such well . . . .” It argued that the rig was necessary to carry  out such activity.
The Fifth Circuit agreed with the district court that “[a]pplying Section 6.2’s expenditure provision to a government-mandated P&A undertaken pursuant to Section 18.4 would lead to an absurd consequence: namely a situation is empowered to hold an operator hostage, preventing the operator from completing a legally required P&A, in order to extract a better bargain or avoid cost-sharing altogether.” Accordingly, whether section 6.2 applied to a section 18.4 undertaking “is ambiguous and was properly put to the jury.”





 pects of a deed of trust. With respect to when a servicer could pay the borrower’s property taxes by the servicer, the key provision used the fact-specific phrase “reasonable or appropriate”; other provisions both suggested that the power was limited to back taxes, but also that it could be made “at any time.” Accordingly, “Wease was entitled to proceed to trial on his claim that Ocwen breached the contract by paying his 2010 taxes before the tax lien attached and before they became delinquent.” This analysis led to finding a triable fact issue as to whether Ocwen provided adequate notice of its actions.
 ned to the “good faith” defense to a claim under the Texas Uniform Fraudulent Transfer Act – a defense that potentially allows an innocent third-party to retain the benefit of a transfer made by a debtor with intent to defraud creditors. The specific question was whether the Texas Supreme Court would accept a “futility” defense to inquiry notice, and the Court concluded that it would not: “No prior court considering TUFTA good faith has applied a futility exception to this exception, and we decline to hold that the Supreme Court of Texas would do so. Transferees seeking to retain fraudulent transfers might offer up evidence of undertaken investigations to prove a reasonable person’s suspicions would not have been aroused when the transfer was received. But the fact that a fraud or scheme is later determined to be too complex for discovery does not excuse a finding of inquiry notice and does not warrant the application of TUFTA good faith.” No. 17-11526 (Jan. 9, 2019).

 (4) a Daubert challenge to the plaintiff’s expert on warnings